
📌 EMPA Short Take:
Professional and general liability insurance may be enough for some energy healers, but it doesn't protect against every financial risk involved in running a practice. Depending on how you work, you may also want protection for business equipment, lost income following a covered event, or sensitive client information. The key is understanding what your current policies cover, what they exclude, and which risks you're comfortable handling yourself. As your practice changes, your insurance needs may change, too.
When you purchase liability insurance for your energy healing practice, there's a certain peace of mind that comes with knowing you've taken steps to protect yourself and your work.
That sigh of relief is as important as it is reassuring!
Although as your practice continues to take shape, you may find there's more to think about than what happens if a client files a claim.
What about the equipment you've invested in over the years? The income you depend on from seeing clients? Or the personal information people trust you to keep safe?
Would your current policy help if something happened in one of those areas?
At EMPA, one thing we've learned from helping practitioners navigate professional and general liability insurance is that coverage questions often come down to understanding your needs.
A policy may be doing exactly what it was designed to do, while leaving other business risks for you to manage.
That doesn't mean everyone needs additional types of protection. It means knowing what you have, recognizing what you may need, and making informed choices as your practice evolves.
In this article, we'll explore where professional and general liability insurance fit into that picture, when other types of protection may be worth considering, and how to decide what makes sense for your healing practice.
 What Does Foundational Liability Insurance Cover for Energy Healers?
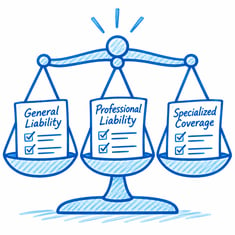
When we say “foundational coverage,” we are referring to professional and general liability insurance. This is at the center of what we provide our members at EMPA!
Together, these two types of insurance address important risks you face when working with clients, but each serves a different purpose.
➡️Professional liability insurance relates to the professional services you provide. If a client claims they were harmed during a healing session or as a result of your professional work, this coverage may help with legal defense costs and other covered expenses.
➡️General liability insurance addresses certain accidents that can happen around your business, rather than during the healing work itself. Imagine a client visiting your practice who trips over a bag near the doorway and gets injured. If they hold you responsible, general liability insurance may help with that claim.
If you're offering Reiki, sound healing, spiritual healing, Healing Touch, or another approved modality, having both types of coverage gives you an important layer of protection as you work with clients.
So, is that enough? For some practitioners, it certainly can be. For others, the answer depends on what else is involved in running their healing practice.
💡Wondering what professional and general liability insurance should cost? Learn what affects pricing, what coverage may include, and what to consider before choosing a policy in our article: Liability Insurance for Energy Healers: Cost, Coverage, and the Real Price of Going Without.
 When Should Energy Healers Consider Additional Insurance Coverage?
Professional and general liability insurance help address covered claims against you. But what if something happens to your equipment, your income, or the client information you keep?
That's where other types of insurance can serve a different purpose. Rather than providing more of the same liability protection, they can help with specific financial risks involved in running your healing practice.
 What If Your Healing Equipment Is Damaged or Stolen?
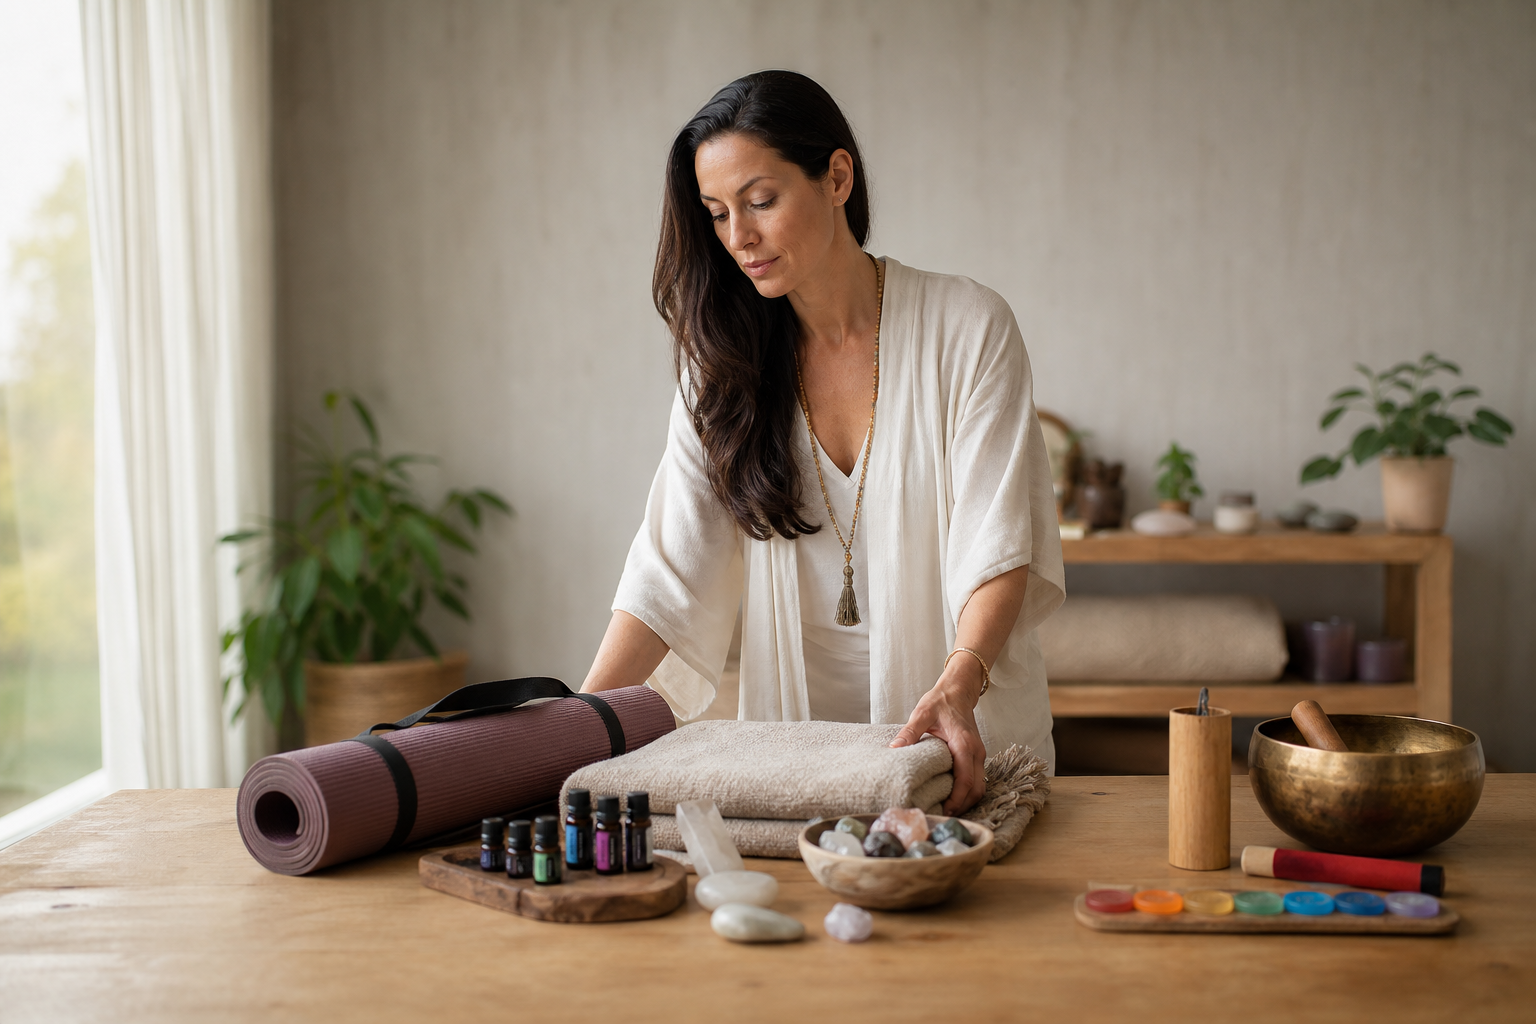
If you work with singing bowls, tuning forks, massage tables, or specialized healing devices, you know how quickly the investment in your tools can add up.
Imagine a fire damages the equipment in your treatment room. You haven't injured a client, and no one is suing you, but you still have thousands of dollars' worth of equipment to replace.
Business personal property insurance is designed to help repair or replace covered business equipment and supplies after an insured loss.
This is especially important if you work from home. Your homeowners insurance may offer very limited protection for business property, so it's worth checking rather than assuming your healing tools are covered.
💡Do you see clients from home? Your homeowners insurance may not protect your business activities or healing equipment the way you expect. Learn what to check in our article: Does Homeowner’s Insurance Cover My At-Home Energy Healing Practice?
At EMPA, our Professional and Premium Protection levels include $10,000 in business personal property coverage, with options to purchase higher limits.
 What If You Have to Temporarily Stop Seeing Clients?
Now imagine that same fire leaves your studio unusable for several weeks.
Replacing your equipment is one concern. But what happens to the income you would normally earn from appointments during that time? What if you're still responsible for rent or other ongoing expenses?
Business income and extra expense insurance can help with lost income and certain additional costs when a covered event interrupts your operations.
EMPA's Professional and Premium Protection levels include $10,000 in business income and extra expense coverage, with higher limits available.
It's worth considering how long your practice could manage financially if you couldn't see clients for a while.
 What If Your Client Information Is Exposed?
Whether you see clients in person or remotely, you may use online scheduling systems, digital intake forms, or electronic client records.
If someone gains unauthorized access to that information, the consequences can extend beyond fixing your computer. Depending on the circumstances, you could face expenses related to investigating the incident, notifying affected clients, and responding to privacy claims.
Cyber liability insurance is designed to help with certain financial and legal costs associated with covered data breaches.
If you are considering joining EMPA, cyber protection is available as an optional add-on.
 What If Your Work Involves Additional Risks?
Some practitioners offer hands-on services, lead workshops, or work with larger groups. These activities can introduce considerations that aren't identical to those of a practitioner seeing individual clients in a private treatment room.
For example, if your work involves physical contact, you may want to understand how your policy addresses allegations of inappropriate touch or misconduct.
If you teach classes or facilitate group activities, you'll also want to confirm that your group size and activities fall within your policy's terms.
EMPA offers optional sexual misconduct and abuse protection for Professional and Premium members, along with included client accident benefits at those membership levels. The appropriate protection depends on the services you provide and the membership coverage you select.
 How Do You Know If Your Energy Healing Practice Needs Additional Insurance?
One thing we've learned from working with energy healing practitioners is that what feels like a gap in insurance coverage can sometimes be a gap in understanding. A policy may be doing exactly what it was designed to do, but if your provider doesn't know the full scope of your practice—or you haven't reviewed the exclusions—you might expect protection that isn't there.
Maybe you've added a new modality, started seeing clients from home, or invested in equipment you didn't own when you first got insured. Or perhaps you've simply never had a conversation about what your policy does and doesn't cover.
Your insurance provider needs a clear picture of your work to help you understand which protections may be appropriate. And you deserve to know what you're paying for, including the risks you're choosing to manage yourself.
Before deciding whether you need additional insurance, take a few minutes to ask yourself:
-
Have I shared the full picture of my practice? Does my insurance provider know which modalities I offer, where I work, whether I teach classes or workshops, and what equipment I use?
- Do I understand what my current policies cover? Have I reviewed the limits, exclusions, and conditions, or am I assuming certain situations are covered because I have liability insurance?
- Has anything changed since I purchased my coverage? Have I added services, moved locations, purchased expensive equipment, or grown my business?
- What would be difficult for me to replace or recover from? If I lost my equipment or couldn't see clients for several weeks, how would that affect my finances?
- Which risks am I comfortable handling myself? Could I afford to replace certain items or manage a temporary loss of income without insurance assistance?
There isn't one right answer for every energy healer or holistic practitioner.
If you're just starting out with a small practice and could comfortably replace your equipment or manage a temporary interruption in income, you may decide that additional protection isn't necessary right now.
On the other hand, if your livelihood depends on specialized equipment, a rented studio, or a steady schedule of client appointments, those same risks may carry greater financial consequences.
The important thing is to make that choice with a clear understanding of your coverage, rather than discovering an exclusion or limitation when you need to make a claim.
One last tidbit: reviewing your insurance isn't something you only do when it's time to renew. As your healing practice grows and changes, it's worth checking in with your insurance provider to make sure your protection still reflects the work you're doing today.
 What’s Next: Professional and General Liability vs. Additional Insurance – What Makes Sense for You?
Professional and general liability insurance may be enough for your healing practice. Additional protection becomes worth considering when there are other financial risks you wouldn't feel comfortable managing on your own.
Neither choice is automatically right for everyone. What matters is understanding the difference, knowing what your policies cover, and making a decision that fits the way you work.
If you're unsure, start by reviewing your current policy and talking with your insurance provider. You can ask questions, clarify exclusions, and make sure your protection reflects the healing practice you have today.
And as that practice grows, you can revisit those choices with confidence.
💡 Ready to explore your insurance options? Knowing what coverage you need is one thing. Knowing what to look for when comparing policies is another! Our free Energy Healer's Insurance Buyer's Guide can help you evaluate your options, ask the right questions, and choose protection that fits your practice.
 Frequently Asked Questions
Is professional liability insurance the same as general liability insurance?
No. Professional liability insurance addresses certain claims related to the healing services you provide, while general liability insurance addresses certain accidents associated with your business, such as a client slipping and getting injured at your practice. Both can be important, but they protect against different types of claims.
How much does professional and general liability insurance cost compared to additional coverage?
For many energy healers and holistic practitioners, professional and general liability insurance costs approximately $100-$275 per year. Plans with additional protections, larger-group coverage, or higher-risk modalities can cost around $375-$500 annually. These ranges reflect EMPA's research into professional liability insurance options available to energy and holistic practitioners, including differences in pricing, coverage, and policy features.
Does liability insurance cover my healing equipment when I travel to clients?
Not automatically. Professional and general liability insurance generally aren't designed to insure your own equipment against damage or theft. If you travel with singing bowls, a massage table, or other tools, ask whether your business property coverage protects those items away from your primary practice location.
Can I add insurance coverage later as my healing practice grows?
Often, yes, depending on your insurance provider and policy options. However, new or expanded coverage generally won't protect you retroactively against losses that occurred before it took effect. It's worth reviewing your needs before introducing a new modality, opening another location, or making a major equipment investment.
Does having additional insurance mean every claim or loss will be covered?
No. Every insurance policy has its own terms, limits, conditions, and exclusions. Additional coverage can address risks that foundational liability insurance doesn't, but no policy covers every possible situation. Understanding those details is just as important as choosing the type of insurance.
Disclaimer: This article is for educational purposes only and does not provide legal, financial, or medical advice. The examples are general, and coverage may vary by policy. Always refer to your insurance provider or policy language for specific details, as the policy terms take precedence. For legal concerns related to your practice, consult an attorney.
Topics: